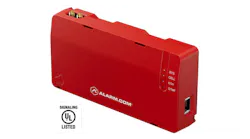
Alarm.com Reports 9% Revenue Growth, Acquires CellGate
Key Highlights
-
Alarm.com reported third-quarter revenue of $279.4 million, up 9% year over year, and raised its full-year outlook.
-
The CellGate acquisition expands Alarm.com's access control portfolio and opens opportunities in the fence and gate contractor market.
-
New video products and AI Deterrence enhancements broaden service provider offerings as hardware costs pressure margins.
Alarm.com (Nasdaq: ALRM) reported third-quarter 2026 revenue of $279.4 million, up 9% year over year, as recurring revenue growth and demand for video products helped the company exceed its expectations. The company also raised its full-year outlook and announced the acquisition of CellGate, expanding its commercial security portfolio.
The results reflect continued growth in Alarm.com’s subscription-based business, while new camera offerings and the CellGate acquisition create additional opportunities for security service providers and contractors. Management also addressed hardware cost pressures, pricing changes and the potential implications of ADT’s pending acquisition by Thrive Holdings.
Recurring revenue growth supports higher guidance
SaaS and license revenue increased 9% year over year to $191.2 million, exceeding the midpoint of management’s guidance by approximately $1.3 million. Revenue retention remained in the 95% range, while the company’s core North American residential business performed in line with expectations.
Hardware and other revenue rose 8.9% to $88.3 million, with higher unit volumes accounting for approximately half of the sequential increase in hardware revenue. Video doorbells contributed the largest share of that volume-driven growth.
Adjusted EBITDA increased 19.3% to $66.2 million, although management cautioned that the quarter benefited from temporary hardware cost recoveries.
CellGate acquisition opens new contractor channel
Alarm.com’s acquisition of CellGate expands its commercial access control capabilities and establishes a presence in the fence and gate contractor market.
CellGate provides cellular-connected gate access and video intercom products for commercial properties, small businesses, multifamily communities and other properties. Its systems support vehicle and pedestrian access without requiring a wired network connection or property Wi-Fi.
“CellGate brings together several characteristics we look for in an acquisition: a specialized product offering, an established relationship with the trade channel, and an opportunity to build recurring services around connected devices,” said Steve Trundle, Alarm.com’s CEO.
Management estimates that as many as 6,000 U.S. fence and gate service companies regularly install automated gates.
CellGate will operate independently, similar to Alarm.com’s OpenEye and CHeKT businesses, with plans for future integrations into the broader platform.
The company expects CellGate to contribute between $15 million and $20 million in SaaS and license revenue during 2027, although its adjusted EBITDA margins are expected to be dilutive for the next couple of years.
Video portfolio adds installation flexibility
Alarm.com introduced a battery-powered video doorbell designed for locations without existing doorbell wiring, including detached garages and secondary entrances.
The customer-installable device supports familiar face recognition, with AI Deterrence capabilities planned for a future release. Its installation approach also allows service providers to offer upgrades without dispatching technicians.
An upgraded indoor camera adds four-megapixel imaging, integrated illumination and a physical privacy shutter. The company also expanded its AI Deterrence software with progressive voice warnings that escalate when someone remains in a protected area.
The additions broaden the range of installation options and price points available to Alarm.com’s service provider partners.
ADT transaction draws management attention
Trundle also addressed Thrive Holdings’ announced acquisition of ADT, describing it alongside GTCR’s acquisition of SimpliSafe as evidence of continued investment interest in residential security.
“When substantial investment flows into our industry, it tends to provide the overall market, including our service providers, our manufacturing partners, banks, and other investors, confirmation that the industry is deserving of capital,” Trundle said.
Alarm.com expects to continue supporting ADT as a major residential and small-business customer.
“While we are optimistic that the Thrive deal will create opportunities to unlock growth for ADT, we are currently modeling the business contribution to Alarm.com the same way we had been prior to the announcement of the acquisition,” Trundle said.
Hardware costs pressure near-term margins
Hardware gross margin reached 28.4% in the third quarter, benefiting from approximately $3.8 million in temporary tariff-related cost recoveries.
CFO Kevin Bradley said those benefits will not continue into the fourth quarter, when higher memory costs are also expected to pressure margins.
Management projects fourth-quarter hardware gross margin of approximately 20.5%, with hardware-related effects creating a $6.6 million sequential adjusted EBITDA headwind.
The company intends to pass through external cost increases without adding another markup.
“We believe passing through these external and somewhat extraordinary cost increases without an additional markup from Alarm.com is the right approach for our service provider partners and their customers, reinforcing the long-term alignment that underpins our business model,” Bradley said.
Outlook points to continued subscription growth
Alarm.com raised its full-year 2026 SaaS and license revenue guidance to between $756.1 million and $756.3 million, representing approximately 9.7% annual growth. Its adjusted EBITDA outlook increased to between $227 million and $229 million.
Preliminary 2027 projections call for SaaS and license revenue of $815 million to $820 million, total revenue of approximately $1.175 billion to $1.19 billion and adjusted EBITDA of $240 million to $245 million.
Management anticipates a full-year 2027 adjusted EBITDA margin of approximately 20.5%, with hardware costs and reinvestment decisions influencing its ability to reach a previously established year-end margin target in the 21% range.
Formal 2027 guidance is expected when Alarm.com reports fourth-quarter results early next year.
(Editor’s note: This article was produced with the assistance of generative AI using Alarm.com's publicly available earnings call transcript as source material. The content was reviewed, edited and verified by the SecurityInfoWatch editorial team to ensure accuracy, context and adherence to our editorial standards.)